Free CII R04 Mock Exam Questions with Answers (2026)
Try 5 free R04 practice questions with answers and explanations — covering pension saving attitudes, the new allowances, net pay vs relief at source, PCLS limits and overseas transfers.
Looking for free CII R04 practice questions? Here are 5 exam-style questions covering a range of learning outcomes, with answers and detailed explanations.
The questions include both standard MCQs and a multiple-response question, just like the real R04 exam. Try each one, then click to reveal the answer and explanation.
📝 R04 Exam Quick Facts
- 50 questions in 1 hour: 39 standard MCQs + 11 multiple-response
- Pass mark: 65% (at least 33 out of 50)
- Multiple-response questions: LO5 (2), LO6 (4) and LO8 (5) — marked all-or-nothing
- Syllabus: HMRC pensions tax regime, DB and DC schemes, state pension, drawing benefits, retirement planning
---
Question 1: LO1 — Attitudes to Pension Saving
Which reason is most often given by people who are not saving enough for retirement?
A. They feel they cannot afford to save
B. They expect to keep working beyond State Pension age
C. They do not trust financial advisers
D. They assume their employer will provide a defined benefit pension
Click to reveal answer
✓ Correct Answer: A
They feel they cannot afford to save.
Affordability is the reason most often cited for under-saving. Other factors — such as believing the State will provide, seeing pension saving as a low priority, or distrust of financial products — are mentioned less frequently in surveys.
LO1 tests the political, economic and social context of pensions. These questions tend to be factual and straightforward — free marks if you've studied the material.
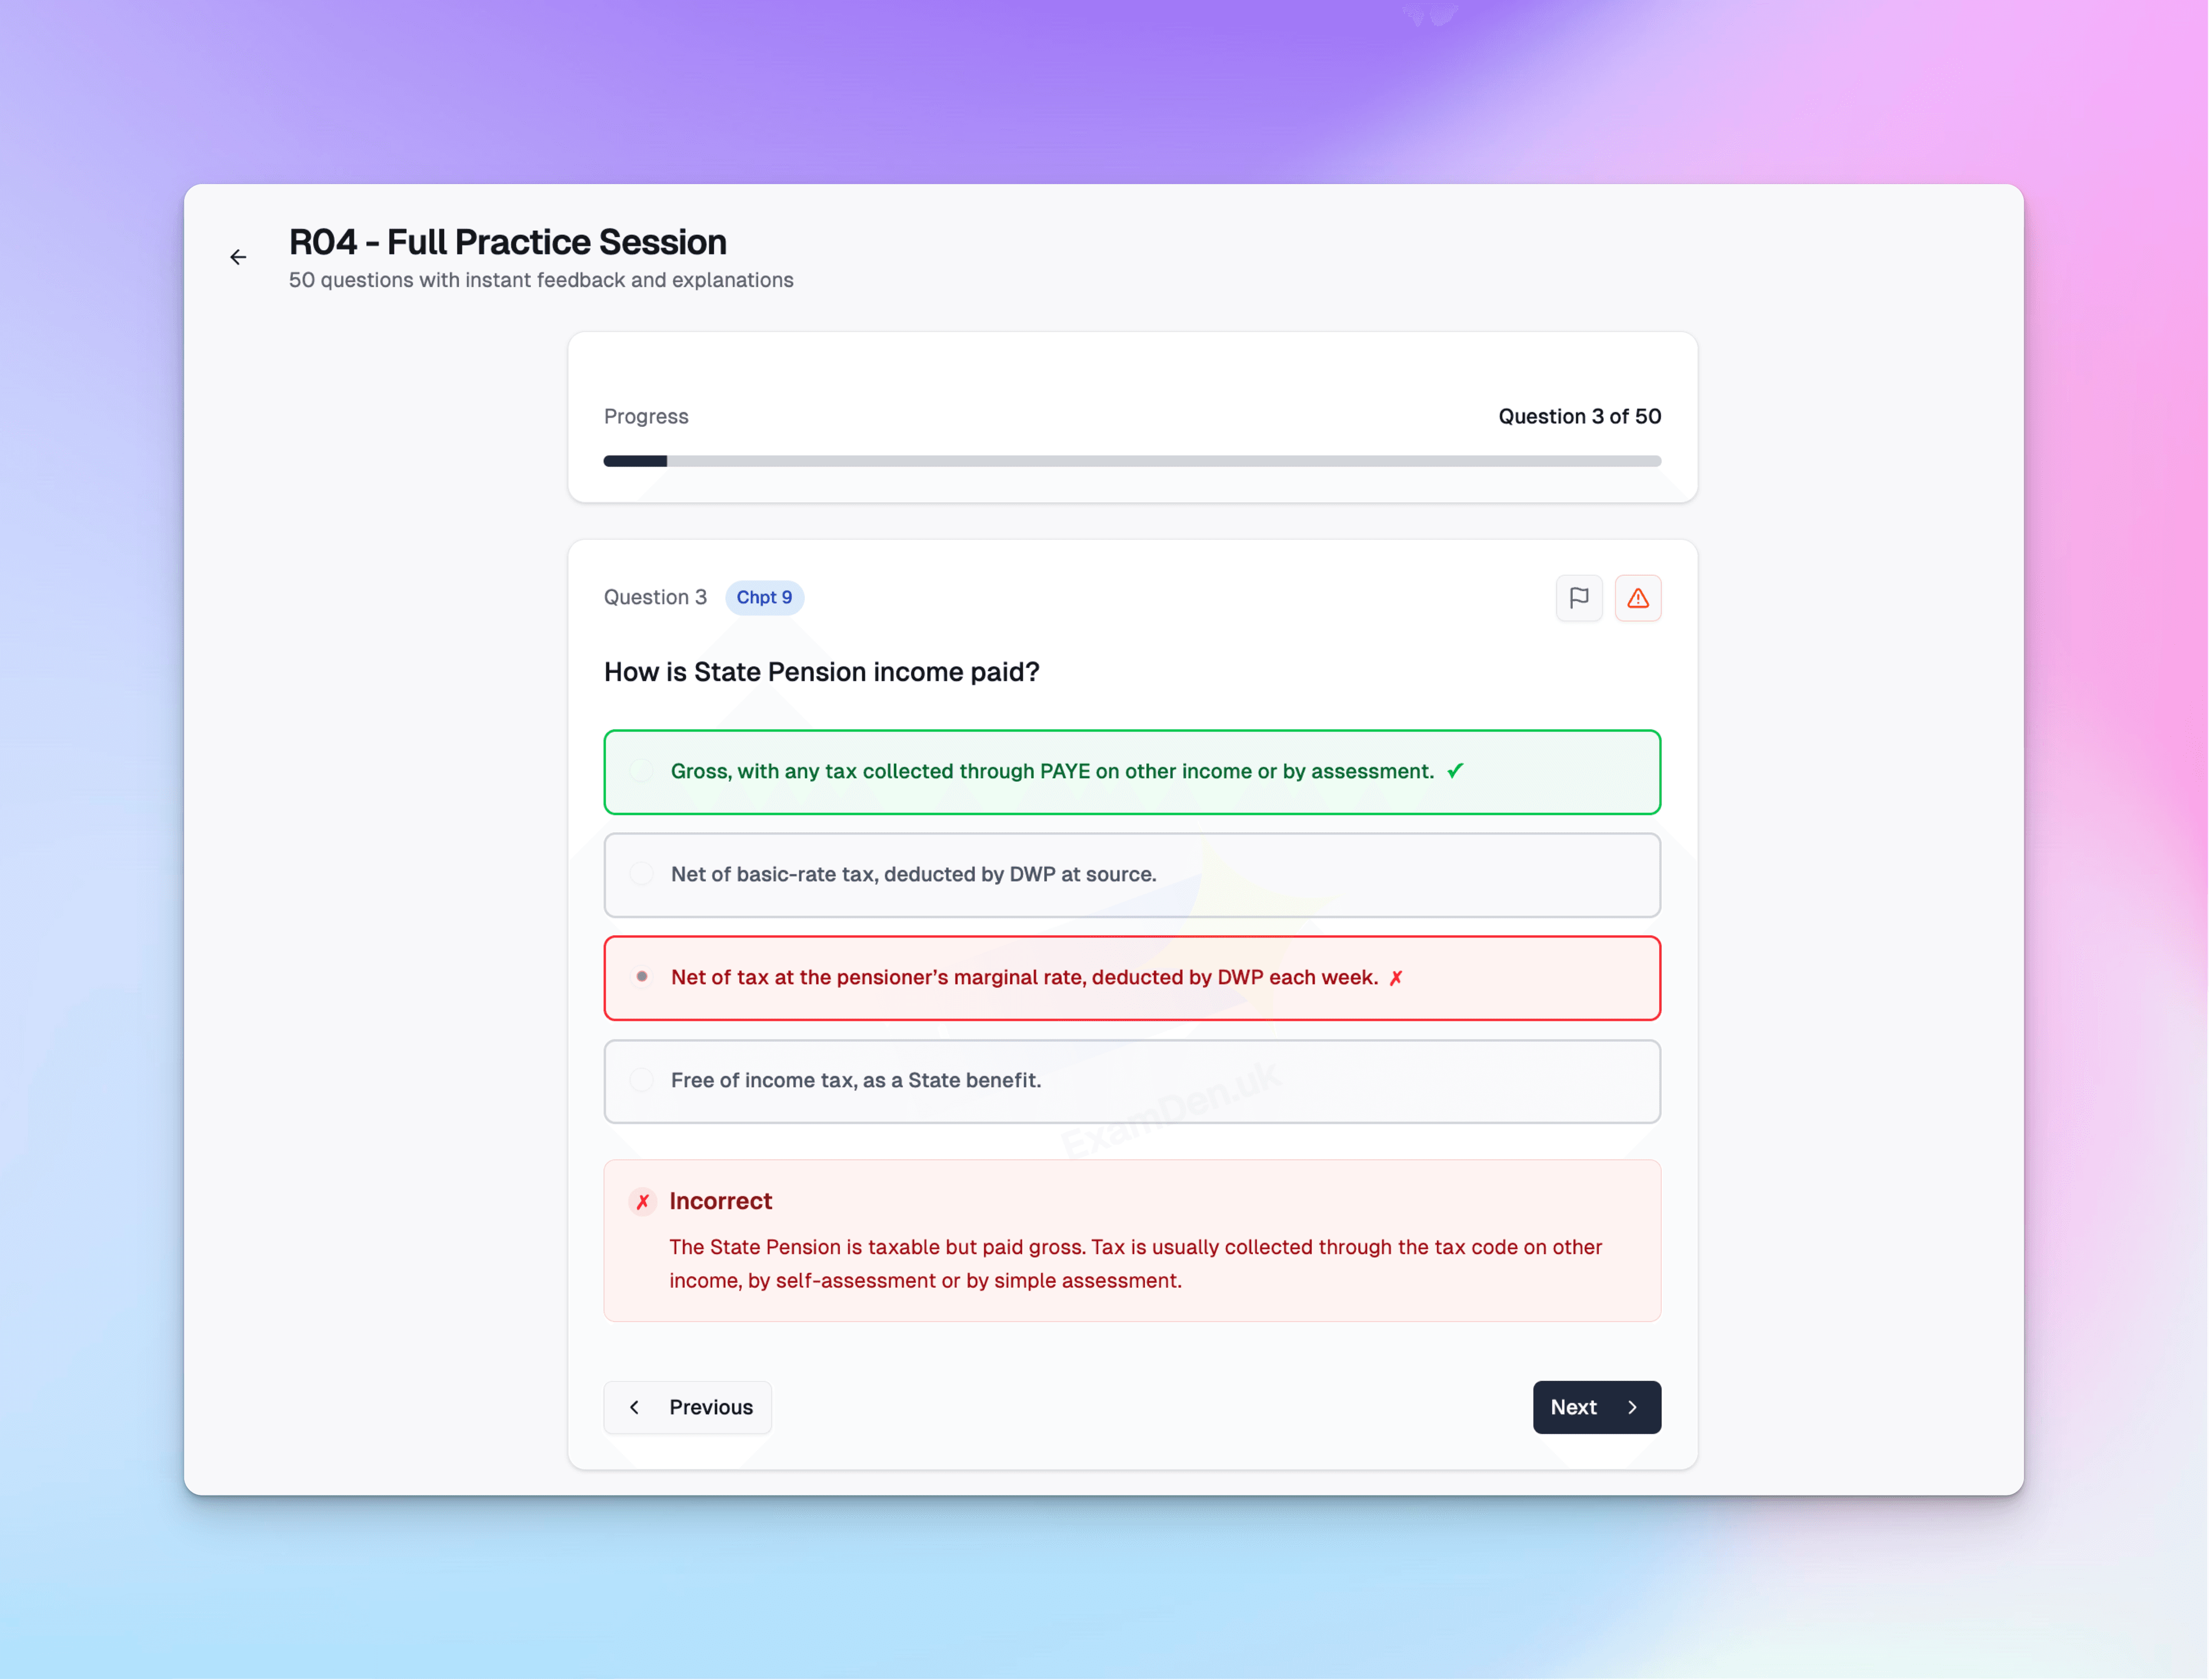
On ExamDen.uk, every question comes with a detailed explanation, like the sample question above
Question 2: LO2 — Pension Policy Measures (Multiple Response)
More than one option is correct. Select all that apply.
Which of the following pension policy measures apply in 2026/27?
A. The lifetime allowance has been replaced by the lump sum allowance and the lump sum and death benefit allowance
B. Members must buy an annuity with their remaining pension fund by age 75
C. Up to £500 a tax year can be taken from a DC pot to pay for pensions advice
D. The normal minimum pension age is 57 for anyone without a protected pension age
Click to reveal answer
✓ Correct Answers: A and C
The LTA replacement and the pensions advice allowance both apply.
The lifetime allowance was abolished from 6 April 2024 and replaced by the lump sum allowance (LSA) and lump sum and death benefit allowance (LSDBA). The pensions advice allowance lets up to £500 a tax year (up to three times) be taken from a DC pot to pay for regulated pensions advice.
Compulsory annuity purchase ended in 2011. The normal minimum pension age is 55 in 2026/27 — it rises to 57 from 2028, but not yet.
This is a multiple-response question — R04 has 11 of these. They're marked all-or-nothing: selecting A but missing C would score zero.
Question 3: LO2 — Tax Relief on Pension Contributions
Tanya is a higher-rate taxpayer who contributes to her employer's occupational pension scheme through a net pay arrangement.
How does she receive tax relief on her contributions?
A. At the basic rate immediately, with higher-rate relief claimed through self-assessment
B. At the basic rate only, immediately
C. At her marginal rate, immediately
D. All relief is claimed through self-assessment
Click to reveal answer
✓ Correct Answer: C
At her marginal rate, immediately.
Under a net pay arrangement, the employer deducts the pension contribution from gross pay before PAYE is applied. Tanya therefore gets relief straight away at her highest rate of tax, with no claim needed.
Option A describes relief at source — a different method where basic-rate relief is added by the pension provider and higher-rate relief must be claimed via self-assessment. Knowing the difference between these two methods is a core R04 topic.
On ExamDen.uk, practise one learning outcome at a time, then sit a full mock in the real question count and time limit
🎯 Practise Like the Real Exam
ExamDen.uk tracks your score by learning outcome so you see exactly where you're losing marks. No more guessing which topics to revise.
Start R04 Practice →Question 4: LO2 — Lump Sum Allowance (Calculation)
Amir has uncrystallised pension funds of £1,400,000, no transitional protection and has never drawn any benefits.
What is the largest tax-free lump sum he can take if he crystallises the whole fund in 2026/27?
A. £268,275
B. £312,500
C. £350,000
D. £375,000
Click to reveal answer
✓ Correct Answer: A
The largest tax-free lump sum is £268,275.
A pension commencement lump sum (PCLS) is limited to the lower of 25% of the amount crystallised and the available lump sum allowance (LSA).
Step 1: 25% of £1,400,000 = £350,000
Step 2: The LSA is £268,275 — this is the cap
Since £350,000 exceeds the LSA, the tax-free lump sum is capped at £268,275. This type of question tests whether you know the new LSA regime that replaced the lifetime allowance.
On ExamDen.uk, timed mocks use the same question count, time limit and pass mark as the real exam
Question 5: LO5 — Overseas Pension Transfers
Joe transfers his UK pension to an overseas scheme that is a recognised overseas pension scheme but not a QROPS.
How is the transfer treated?
A. As a recognised transfer, tested against his overseas transfer allowance
B. As a relevant benefit crystallisation event
C. As tax-free, as long as he lives in that country
D. As an unauthorised payment, subject to tax charges
Click to reveal answer
✓ Correct Answer: D
An unauthorised payment, subject to tax charges.
Only transfers to a qualifying recognised overseas pension scheme (QROPS) are treated as recognised transfers. A transfer to any other overseas scheme — even if it is a "recognised overseas pension scheme" — is an unauthorised payment and attracts the unauthorised payments charges.
This distinction is important: "recognised overseas pension scheme" and "QROPS" are not the same thing. The exam tests whether you know the difference.
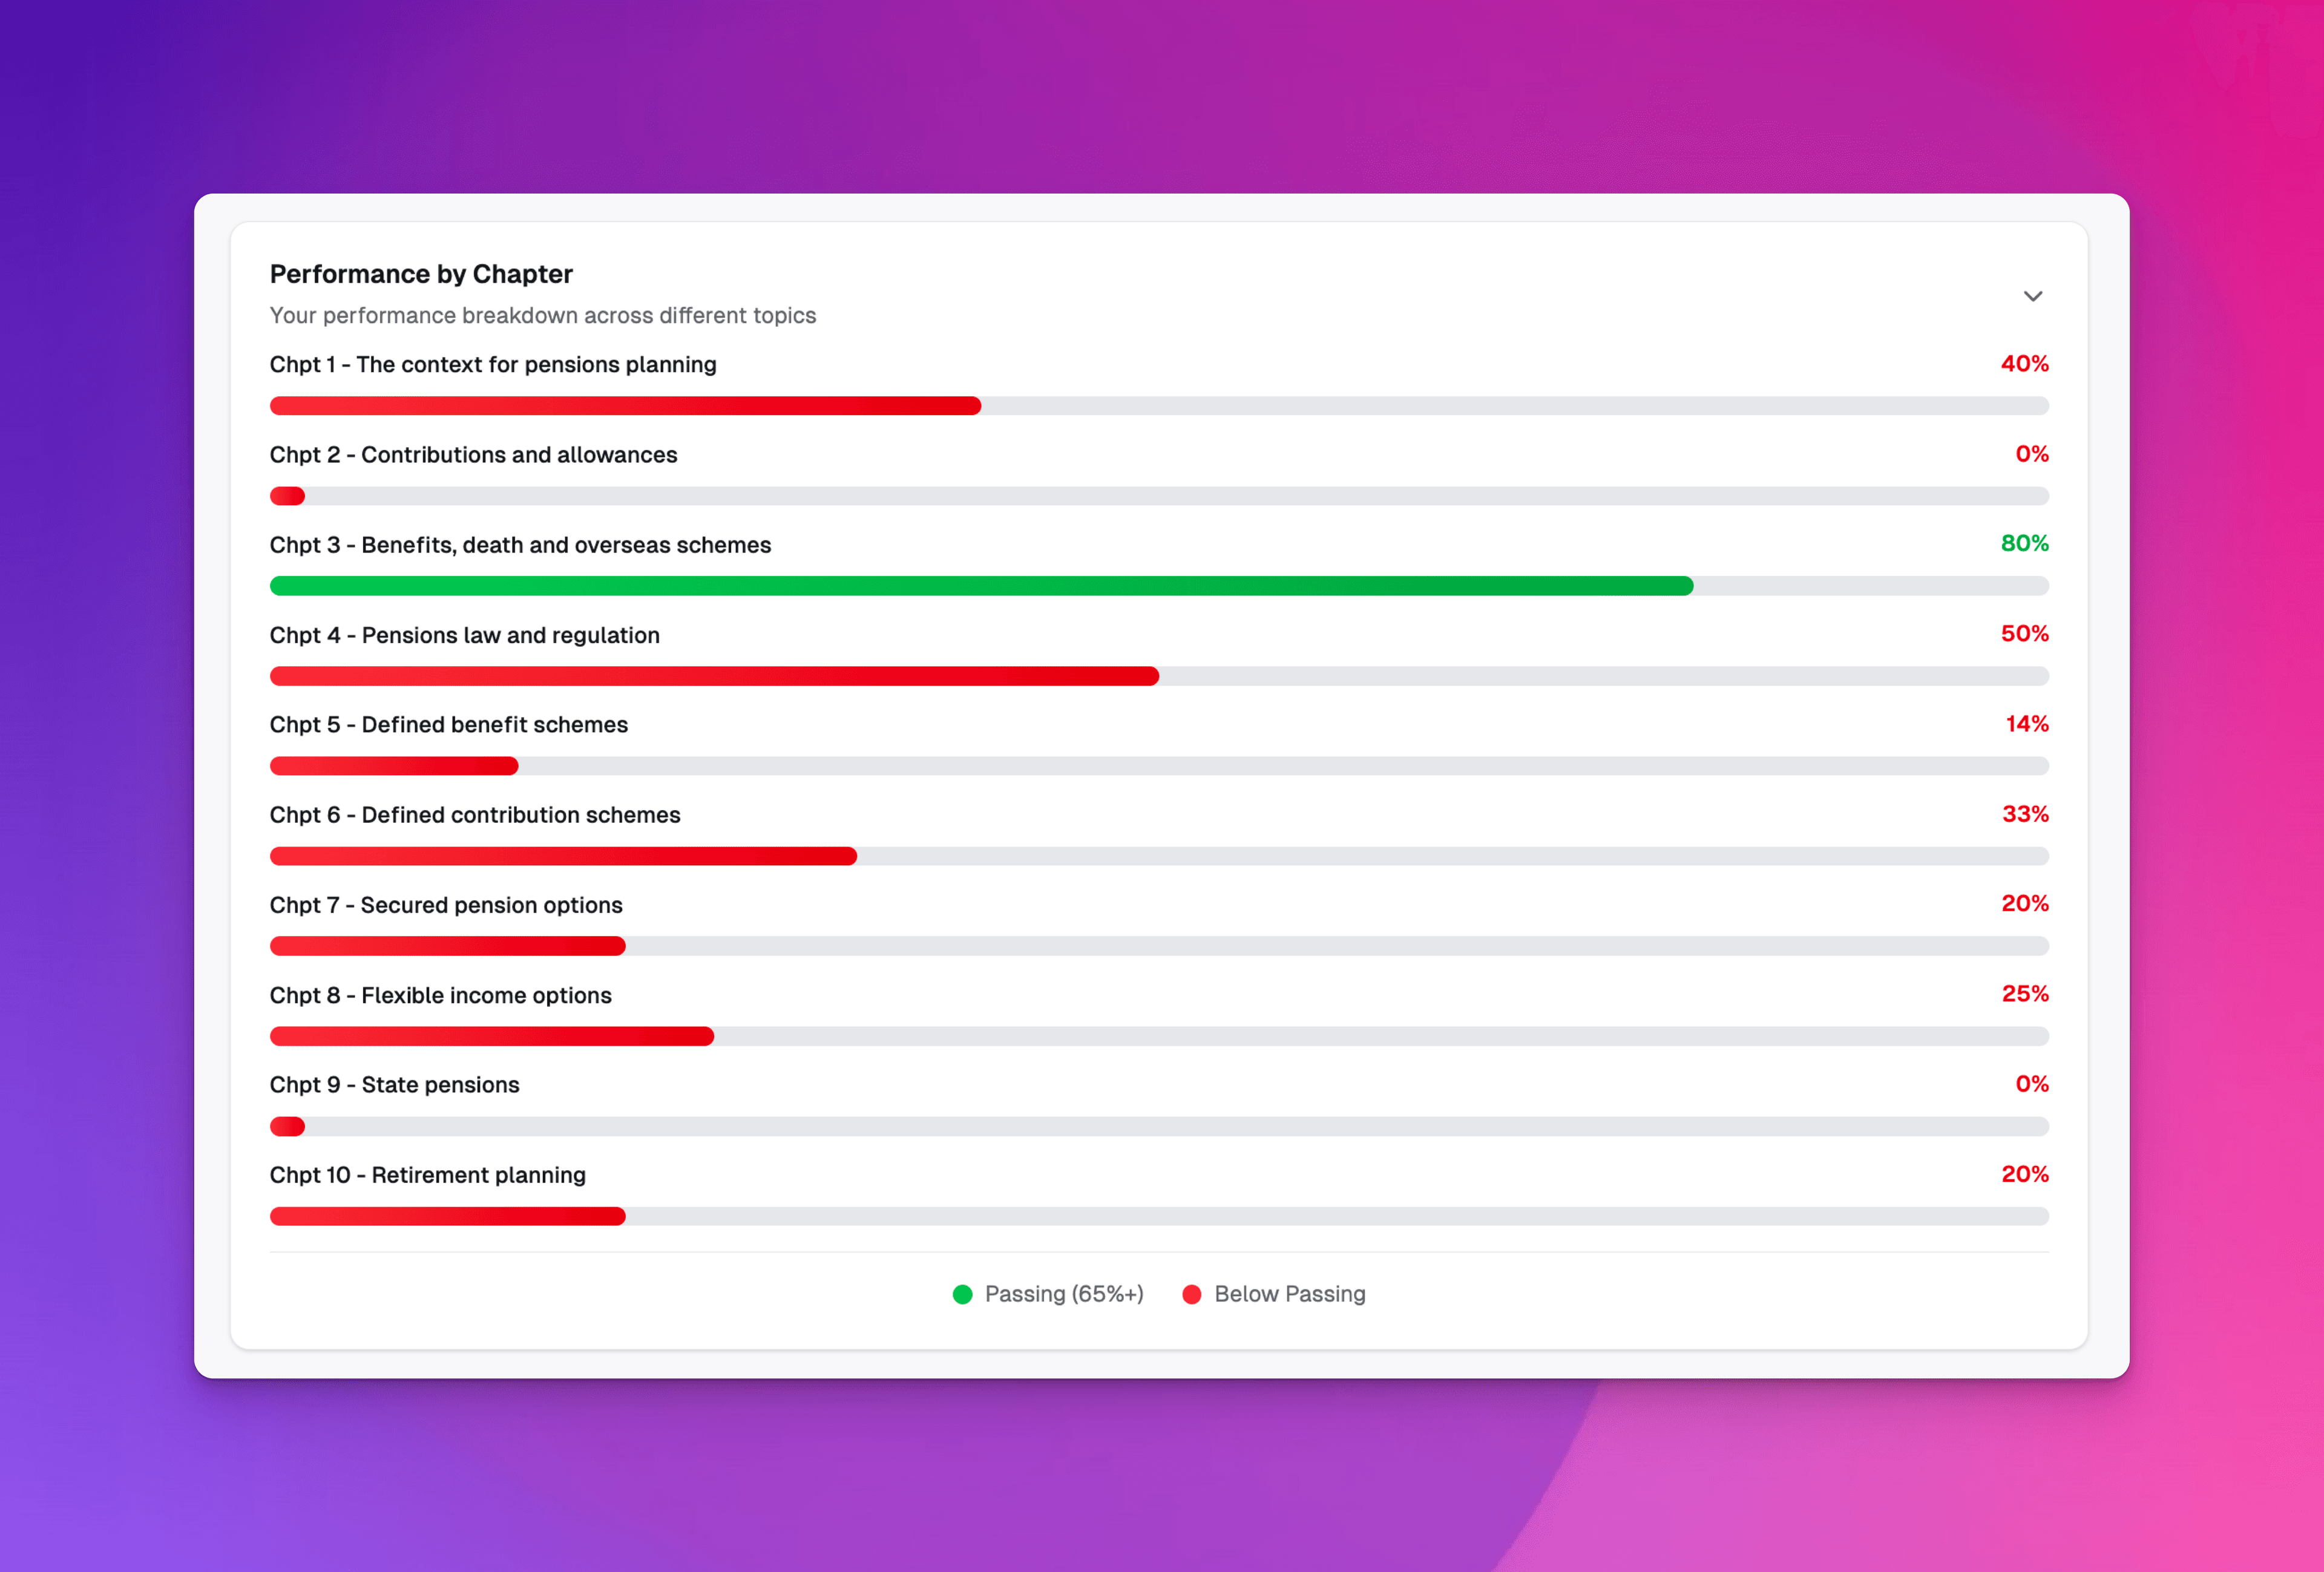
On ExamDen.uk, a timed mock shows your score against the 65% pass mark, and which learning outcomes are below it
How Did You Do?
| Score | What it means |
|---|---|
| 4–5 correct | Strong foundation — you're getting to grips with R04. Focus on timed practice with a larger question set. |
| 2–3 correct | Good start, but some areas need work. Check which learning outcomes you got wrong and revise those. |
| 0–1 correct | More study needed. Review the material before attempting mocks — see our R04 study guide. |
These 5 questions are a small sample. The real R04 exam has 50 questions across 8 learning outcomes, and the only way to know if you're ready is to take a full timed mock.
Want More Practice?
ExamDen's R04 question bank has hundreds of exam-style questions — standard MCQs and multiple-response questions marked all-or-nothing — timed mocks in the real CII format, and AI that pinpoints which learning outcomes to revise.
For a full study plan, see our complete R04 study guide. If you were searching for past papers, read why the CII doesn't release them, and what to use instead.
R04 Practice Questions FAQs
Ready to Put This Strategy Into Action? 💯
Liked these questions? Practise with hundreds more, including multiple-response questions marked all-or-nothing, with timed mocks and AI that tracks your weak areas.
The ExamDen.uk Team
ExamDen.uk builds exam-style question banks and timed mocks for CeMAP, Cert CII and CII R01–R05, helping UK professionals prepare for their financial services exams.